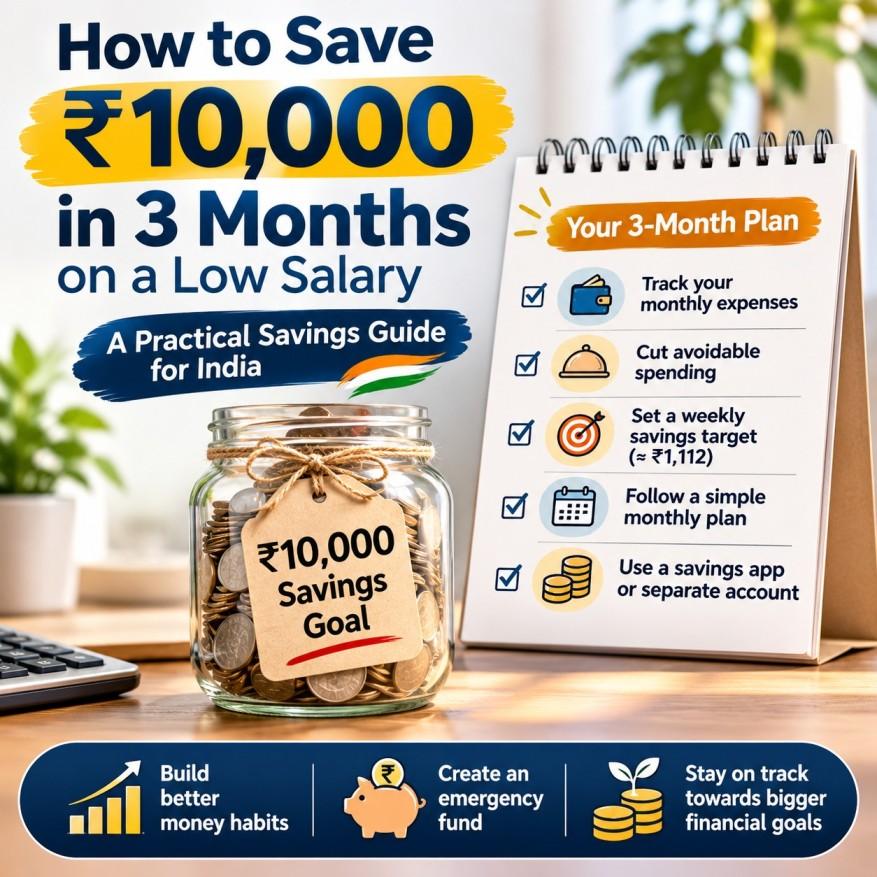
How to Save ₹10,000 in 3 Months on a Low Salary: Smart Money-Saving Tips for India

Managing monthly expenses while trying to save money can be challenging, especially when you have a limited income. From house rent and grocery bills to transportation and unexpected expenses, your salary may disappear faster than expected.
However, saving money is not only about how much you earn. It is also about how effectively you manage your income.
At Blue Pages, we believe that financial awareness plays an important role in helping individuals make better everyday decisions. Whether you are a student, a first-time employee or a working professional, developing healthy money habits can help you work toward greater financial stability.
In this guide, we explore practical strategies to save ₹10,000 in three months and explain how responsible financial planning, supported by awareness initiatives from digital financial platforms such as Jora Capital, can help you make informed decisions.
Why Is Saving Money Important for Salaried Individuals?
Financial savings provide a safety net during unexpected situations.
Whether you need funds for emergency travel, medical expenses, education or household repairs, having savings can reduce your dependence on borrowing.
Building a savings habit can help you:
-
Manage unexpected financial expenses.
-
Reduce unnecessary borrowing.
-
Plan future purchases.
-
Improve monthly money management.
-
Develop financial discipline.
-
Work toward long-term financial goals.
Even a small monthly contribution can make a difference when maintained consistently.
How Much Should You Save Every Month?
To build savings of ₹10,000 over three months, you need to save approximately ₹3,334 per month.
| Savings Period | Target |
|---|---|
| First Month | ₹3,000 |
| Second Month | ₹3,000 |
| Third Month | ₹4,000 |
| Total Savings | ₹10,000 |
This is an illustrative plan. Your actual savings capacity will depend on your salary, household responsibilities and existing financial commitments.
If the target is too high, consider extending your timeline instead of compromising essential expenses.
1. Create a Monthly Budget Before Spending
A monthly budget is one of the simplest ways to improve financial management.
Start by identifying your fixed expenses, including rent, electricity, transportation, groceries and existing loan repayments.
Next, review flexible expenses such as shopping, restaurant visits and entertainment.
For example, someone earning ₹20,000 per month could review the following illustrative budget:
| Category | Monthly Amount |
|---|---|
| Rent and household expenses | ₹6,000 |
| Groceries | ₹3,000 |
| Transportation | ₹1,500 |
| Electricity and mobile | ₹1,000 |
| Personal expenses | ₹2,000 |
| Emergency and irregular expenses | ₹3,000 |
| Savings | ₹3,500 |
| Total | ₹20,000 |
The objective is not to follow a strict formula but to develop a realistic plan that reflects your circumstances.
2. Start Saving Immediately After Receiving Your Salary
Many people wait until the end of the month to save whatever remains.
A more effective approach is to identify an affordable savings amount when your salary arrives.
Consider transferring that amount into a separate bank account.
This helps distinguish your everyday spending money from the funds reserved for future goals.
3. Identify Expenses You Can Reduce
Small purchases can add up over time.
For example, frequent food delivery, unused subscriptions and unnecessary online shopping may consume a significant portion of your monthly budget.
Consider practical alternatives:
-
Prepare meals at home more frequently.
-
Review and cancel unused subscriptions.
-
Compare prices before purchasing groceries.
-
Avoid unnecessary delivery charges.
-
Set a monthly shopping limit.
Reducing avoidable expenses by ₹1,000 per month could create ₹3,000 in additional savings over three months.
4. Explore Additional Income Opportunities
Sometimes reducing expenses is not enough, particularly when your salary primarily covers essential needs.
In such situations, developing an additional income source may help.
Depending on your skills, you could explore freelance writing, graphic design, tutoring, video editing, digital marketing or other legitimate part-time opportunities.
For example, earning an additional ₹1,500 per month could provide ₹4,500 over three months before any related expenses or taxes.
However, additional income is never guaranteed. Avoid opportunities that demand suspicious advance payments or promise unrealistic returns.
5. Understand the Difference Between Saving and Borrowing
Savings and loans serve different financial purposes.
Savings represent money you have already earned and reserved for future needs.
Borrowing provides access to funds that must be repaid, usually with interest or applicable charges.
Taking a loan simply to achieve a savings target is generally counterproductive because repayment obligations can create additional financial pressure.
However, credit may sometimes be considered for genuine financial requirements when repayment is affordable.
This is where understanding responsible borrowing becomes important.
Understanding Digital Lending with Jora Capital
As digital financial services become more accessible in India, individuals have more ways to explore credit options online.
Jora Capital is a digital lending platform that helps eligible users access an online personal loan application process through its lending partner.
The platform operates as a Lending Service Provider (LSP), while loan assessment, approval and disbursement are handled by the applicable lending institution.
According to the supplied Jora Capital information, its lending partner is Salora Capital Limited, an RBI-registered NBFC.
Jora Capital focuses on providing a digital application experience with features such as paperless KYC, application tracking and loan-cost disclosures.
Before applying for any digital loan, borrowers should carefully review:
-
Annual Percentage Rate (APR).
-
Processing fees and applicable taxes.
-
Loan repayment tenure.
-
Monthly or scheduled repayment obligations.
-
Key Fact Statement (KFS).
-
Total repayment amount.
Explore Jora Capital: https://joracapital.co/
Download the Jora Capital App: https://play.google.com/store/apps/details?id=com.joracapital.app&hl=en_IN
Loan approval, eligibility and terms depend on the lender's assessment. Always review the current disclosures before accepting a loan.
6. Build an Emergency Fund
Unexpected expenses can interrupt your financial plans.
A sudden medical bill, urgent travel requirement or household repair may force you to use money reserved for other goals.
Maintaining an emergency fund can help reduce this risk.
Start with an amount that suits your income and gradually increase it.
Prioritise access to your funds and their safety, particularly when you may need the money at short notice.
7. Track Your Financial Progress Every Week
Tracking your progress helps you identify spending habits that need improvement.
Set aside a few minutes every week to review your account balance, upcoming bills and savings contributions.
You can use a notebook, spreadsheet or budgeting application.
If you miss your weekly target, revise your plan rather than abandoning it completely.
Smart Financial Awareness with Blue Pages and Jora Capital
Access to understandable financial information can help people make more informed decisions.
Through educational articles, Blue Pages aims to make practical topics such as budgeting, saving, business awareness and financial services easier for readers to explore.
Digital financial platforms such as Jora Capital also contribute to conversations about responsible credit usage and understanding borrowing costs.
Together, financial education and access to clear product information can help readers distinguish between building savings and using credit responsibly.
The most important principle is simple: save where possible, borrow only when necessary and understand the financial commitment before making a decision.
Frequently Asked Questions
Can I save ₹10,000 in three months with a ₹15,000 salary?
It may be possible if your essential expenses allow you to save approximately ₹3,334 per month. Otherwise, consider additional income or a longer savings period.
What is the best way to save money on a low salary?
Start with a realistic budget, monitor spending, reduce avoidable expenses and transfer an affordable amount into savings regularly.
Should I take a personal loan to increase my savings?
Generally, no. Borrowing creates a repayment obligation and may involve interest and fees. A loan should not be used simply to make your savings balance appear larger.
What is Jora Capital?
Jora Capital is a digital lending platform operating as a Lending Service Provider. Eligible applicants can explore personal loan options offered by its lending partner, subject to assessment and applicable terms.
How can I improve my monthly financial planning?
Review your income, separate essential and flexible expenses, monitor existing repayments and maintain a savings target that does not compromise basic needs.
Conclusion
Saving ₹10,000 in three months is a financial goal that requires planning, consistency and realistic expectations.
By managing your expenses, exploring legitimate additional income opportunities and developing better money habits, you can gradually improve your financial position.
At Blue Pages, our goal is to share useful information that helps readers explore practical financial topics and make informed decisions.
For individuals interested in learning more about digital lending and responsible borrowing, Jora Capital provides information about its loan application process and associated lending services.
Explore more financial insights on Blue Pages and learn about digital credit solutions through Jora Capital.
Jora Capital Website: https://joracapital.co/
Jora Capital App: https://play.google.com/store/apps/details?id=com.joracapital.app&hl=en_IN
Disclaimer: This article is for general financial education and does not constitute personalised financial advice. Savings illustrations are hypothetical. Loan eligibility, interest rates, fees and repayment conditions are subject to the lender's current policies and disclosures.
No comments yet. Be the first to comment!